Quantpedia in July 2026
Hello all,
We hope you’re enjoying the middle of summer, whether you’re relaxing on a beach, hiking in the mountains, or simply trying to find the nearest source of air conditioning. July delivered record temperatures in many parts of the world—and enough market volatility to remind investors that even summer holidays rarely extend to Wall Street…
The Quantpedia team stayed busy, and here’s a quick recap of the latest improvements and additions we’ve prepared for Quantpedia during the past month.
Firstly, one of our key development priorities continues to be the Quantpedia API, available to Quantpedia Pro subscribers. Over the past month, we focused on improving the underlying database infrastructure, streamlining and organizing the data to prepare for a significant expansion of the API’s capabilities in the coming months.
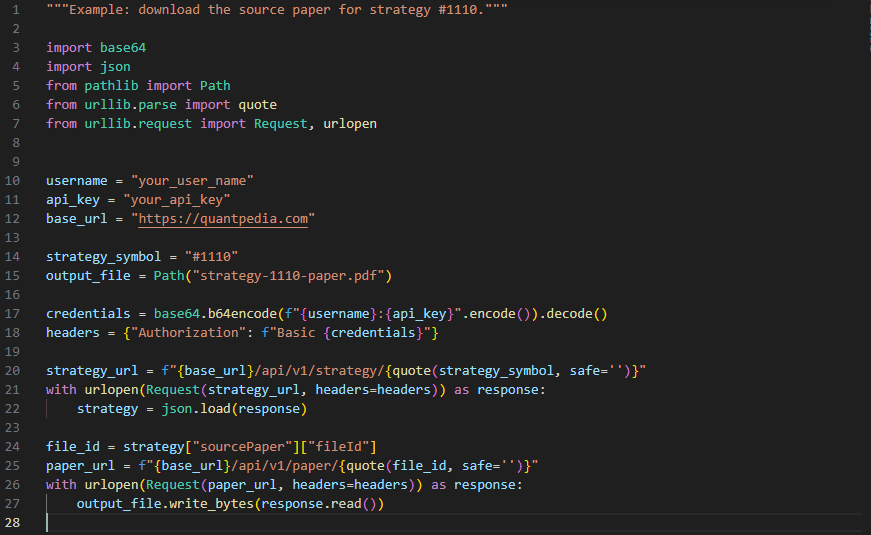
In addition, we introduced a small but useful enhancement for API users. A number of strategies in the Quantpedia database—and their accompanying research papers—are authored by the Quantpedia team. Since we own the rights to these publications, API users can now also directly download the full research papers through the API, making it easier to integrate both strategy data and supporting documentation into automated research workflows. Of course, for strategies based on third-party academic research, copyright restrictions naturally prevent us from distributing the original papers, so the API continues to provide links to the open-access academic repositories.
And secondly, let’s also quickly recapitulate Quantpedia Premium development:
- 10 new Quantpedia Premium strategies have been added to our database.
- 2 new related research papers have been included in existing Premium strategies during the last month
- 7 new backtests were written in QuantConnect code. Our database currently contains, in total, nearly 970 strategies with out-of-sample backtests/codes.
Additionally, 5 new research reviews were published on the Quantpedia blog in the previous month:
Is Trend Still Your Friend?: A Microstructural Account of the Demise of Short-Term Trend-Following
Authors: Jutta G. Kurth, Zoltan Eisler, Adam Rej, Jean-Philippe Bouchaud
Title: Is Trend Still Your Friend?: A Microstructural Account of the Demise of Short-Term Trend-Following
From Backtest to Benchmark: Validating New Strategies with Quantpedia API
Author: David Mesicek
Title: From Backtest to Benchmark: Validating New Strategies with Quantpedia API
Getting the Target Right in Return Prediction
Authors: Nusret Cakici and Adam Zaremba
Title: Getting the Target Right in Return Prediction
Commodity Crisis Analysis – How Portfolios React to Commodity Shocks
Author: David Mesicek
Title: Commodity Crisis Analysis – How Portfolios React to Commodity Shocks
Can AI Do Financial Research?
Authors: Huan Liu, Miao Liu, Zhizhe Liu, and Danqing Mei
Title: Can AI Do Financial Research? LLM-Guided Hypothesis Discovery in Asset Pricing
Yours …
Radovan Vojtko
CEO & Head of Research
Are you looking for more strategies to read about? Sign up for our newsletter or visit our Blog or Screener.
Do you want to learn more about Quantpedia Premium service? Check how Quantpedia works, our mission and Premium pricing offer.
Do you want to learn more about Quantpedia Pro service? Check its description, watch videos, review reporting capabilities and visit our pricing offer.
Do you want algorithmic access to the full Quantpedia database via the API? Subscribe to Quantpedia Pro, ask for an API key, and explore the in/out-of-sample statistics, source academic papers, and code snippets — ideal for quantitative research, systematic trading workflows, and AI model training.
Are you looking for historical data or backtesting platforms? Check our list of Algo Trading Discounts.
Or follow us on:
Facebook Group, Facebook Page, Telegram, Twitter, Linkedin, Medium or Youtube
Share onLinkedInTwitterFacebookRefer to a friend